
November 16, 2026
The finance committee wants to know whether the business should switch from company cars to car allowances. You need a defensible answer by Thursday, and fleet management is competing with the rest of your job for attention.
This comparison covers the UK employer's cost and legal obligations under each model, using HMRC rates that apply from 6 April 2026. Neither option is universally cheaper. The answer depends on each driver's annual business mileage, vehicle grade and fuel type, and on how much fleet risk the employer is willing to carry directly. Salary sacrifice is a third model, outside the scope of this comparison. The employee's personal tax position under each model is a separate calculation.
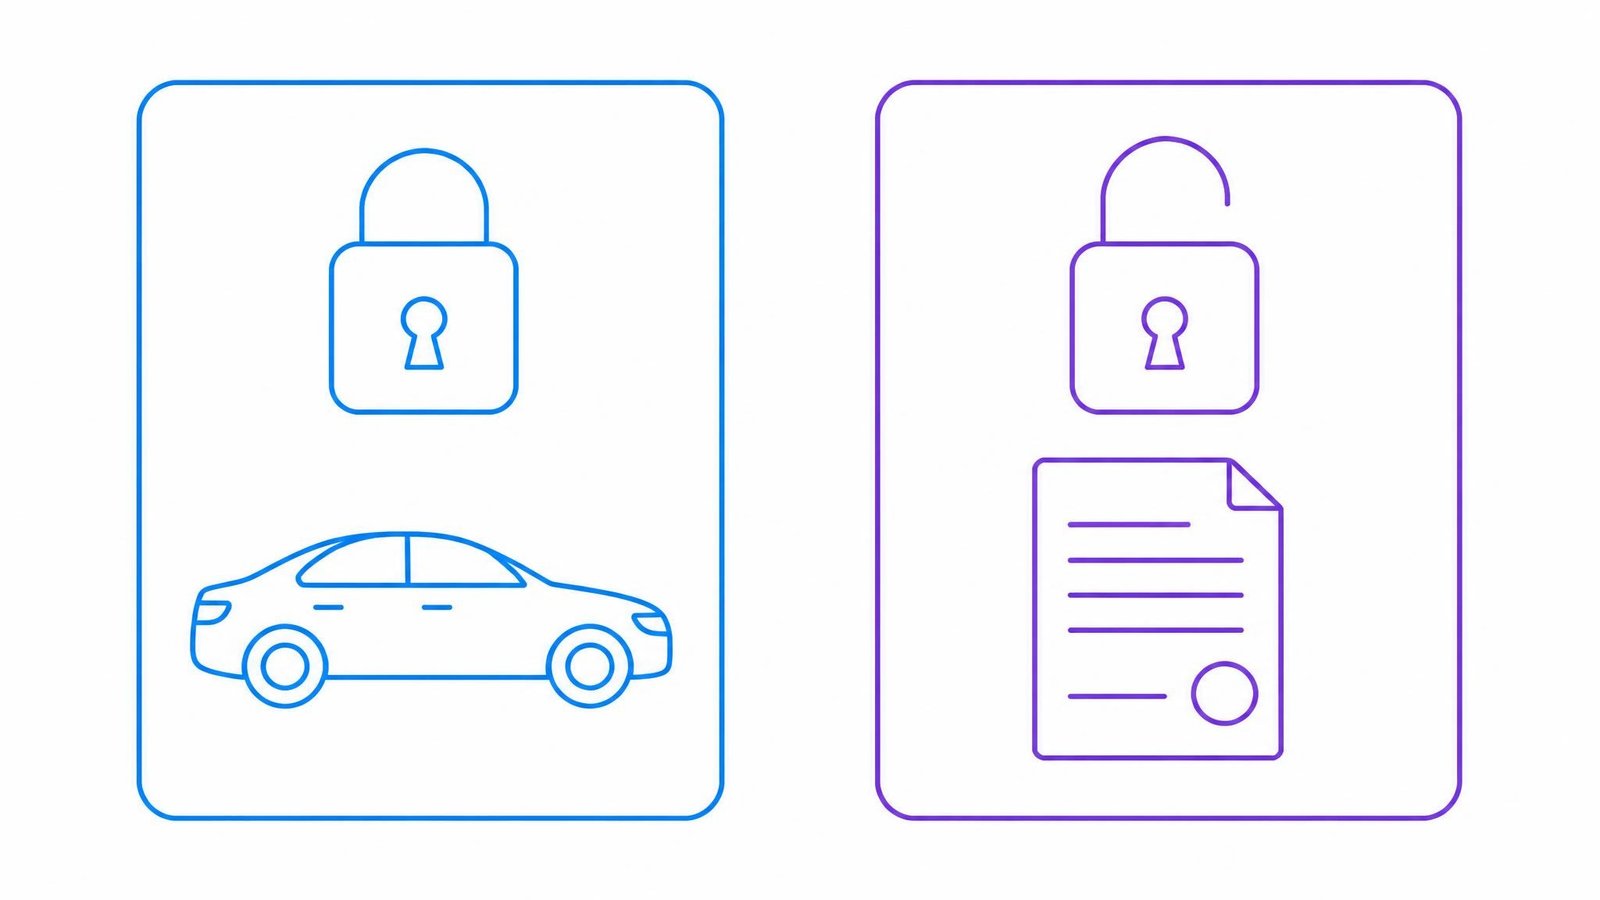
Under a company car scheme, the business provides the vehicle. It holds the lease or finance agreement, arranges insurance, manages maintenance, and typically issues a fuel card. Every cost line sits on the employer's ledger and can be audited per vehicle.
Under a car allowance scheme, the business pays a cash sum through payroll. The employee sources, insures and maintains their own vehicle. A vehicle used this way for business journeys is grey fleet, and the employer's duty of care under the Health and Safety at Work etc. Act 1974 still applies to it.
An employer moving from petrol or diesel to electric company cars reduces its Class 1A NIC exposure, a cost lever that does not exist under a car allowance.
Technical note: does the allowance count as RME?
It depends on what the allowance is paid for and how the scheme works in practice. HMRC has contested whether lump-sum car allowances count as RME, and tribunals decide it on the facts of each scheme. In Laing O'Rourke and Willmott Dixon v HMRC [2023] UKUT 155 (TCC), the Upper Tribunal found the employers' car allowances were RME on their particular facts.
If the allowance is RME, the qualifying amount shelters part of the combined total from NIC. If it is not, the allowance is ordinary earnings for employer NIC, and the mileage payments are checked separately against the qualifying amount. The qualifying amount cannot be carried forward between earnings periods.
Check the position for your own scheme with your payroll or tax adviser.
| Cost line | Company car | Car allowance |
|---|---|---|
| Lease or finance | Direct employer cost | Not applicable |
| Insurance | Direct employer cost (fleet policy) | Not applicable (employee arranges) |
| Maintenance | Direct employer cost, plus unscheduled risk | Not applicable (employee arranges) |
| Fuel or electricity | Fuel card or charging arrangement; for petrol or diesel, fuel benefit charge + Class 1A NIC if private fuel provided; no fuel benefit charge on electricity | Not applicable |
| Employer NIC | Class 1A at 15% on P11D x BIK % | Class 1 at 15%; on RME above qualifying amount if allowance is RME, or on allowance as earnings + mileage RME separately if not |
| Business mileage cost | Through fuel card (already counted above) | Reimbursement up to approved rates, on top of the allowance |
| Employer duty of care | Standard fleet compliance | Applies: the vehicle is grey fleet and the employer retains the duty |
Which column produces a lower total depends on the allowance level, the driver's annual business mileage, and the vehicle's fuel type.
The numbers below are an illustration, not a quote. Replace every assumption with the actual figure from your leasing provider, insurer and payroll.
Assumptions: one driver, 18,000 total miles per year, 12,000 business miles. Company car is electric with no private fuel provided by the employer. The allowance is set to fund a car of the same standard as the company EV. Private charging is paid by the driver in both models; the employer pays business charging only. Employer Class 1 secondary rate 15%, secondary threshold £5,000 per year (GOV.UK). The driver's salary is already above the secondary threshold, so employer NIC applies to the whole excess. Class 1A rate 15%. Zero-emission BIK rate 4%. NIC is shown on an annual basis for simplicity; payroll applies the qualifying amount per earnings period. The car allowance is assumed to be RME on its facts (see the NIC section above).
Company car
| Line | Basis | Annual cost |
|---|---|---|
| Lease including scheduled maintenance | Assumed | £6,000 |
| Insurance (employer's share per vehicle) | Assumed | £1,200 |
| Business charging cost | Assumed | £1,000 |
| Employer Class 1A NIC | £40,000 P11D x 4% BIK x 15% | £240 |
| Total | £8,440 |
Car allowance
| Line | Basis | Annual cost |
|---|---|---|
| Cash allowance | Assumed | £6,000 |
| Mileage reimbursement at approved rates | 10,000 x £0.55 + 2,000 x £0.25 | £6,000 |
| Employer Class 1 NIC on excess RME | (£12,000 RME - £6,600 qualifying) x 15% | £810 |
| Total | £12,810 |
If the allowance is not RME: employer NIC falls on the £6,000 allowance as ordinary earnings (£6,000 x 15% = £900), while the £6,000 mileage payments stay below the £6,600 qualifying amount and attract no NIC. The allowance total becomes £12,900.
In this scenario the car allowance costs the employer £4,370 more per driver per year (or £4,460 if the allowance is not RME). The gap narrows if the lease cost is higher, if the car is petrol or diesel with a high BIK percentage, or if the driver does fewer business miles, because the mileage payments fall with every business mile.
VAT recovery, corporation tax relief and administration costs are not included.
The employer's duty of care under the Health and Safety at Work etc. Act 1974 applies to every vehicle used for a business journey, whether company-owned or privately funded by a cash allowance.
Under a company car scheme, the employer carries maintenance and compliance risk and keeps operational control: vehicle selection, maximum vehicle age, CO2 limits and ULEZ compliance are procurement decisions. On a contract hire the leasing company carries the residual value risk; an employer that buys outright carries it.
Under a car allowance, the employer transfers those financial risks to the employee, and with the risk goes operational control. The employer cannot dictate which vehicle the employee buys, its age or its emissions rating unless allowance conditions are written into the employment contract and actively enforced. That means verifying MOTs, business-use insurance, driver licences and any emissions or age conditions set by company policy. This is the kind of compliance work fleet management software is designed to handle: documents surface as exceptions before a journey, not after an incident.
Businesses that have committed to emissions targets or ULEZ standards should weigh whether an allowance scheme undermines those commitments by handing vehicle selection to individual employees.
A common error in a company car vs car allowance comparison is assuming the employer NIC position on the allowance side without checking whether the allowance qualifies as relevant motoring expenditure. If it is RME, the qualifying amount shelters part of the combined total from NIC. If it is not, the allowance is treated as ordinary earnings for NIC and the bill changes. Getting this wrong in either direction moves the employer NIC line and can tip the recommendation. The same applies on the company car side if a comparison omits the fuel benefit charge where the employer covers private fuel: the company car column then looks cheaper than it is.
Yes. Any vehicle used for business that is not owned or leased by the employer is grey fleet. The employer's duty of care applies from the moment it is used on a business journey.
The allowance and mileage reimbursement are separate. HMRC sets a tax-free ceiling for mileage payments (55p per mile for the first 10,000 business miles, 25p above that, from 6 April 2026), but how much the employer pays is a contractual matter, not a tax obligation. If the employer reimburses below the approved rates, the employee can claim Mileage Allowance Relief on the difference.
Employer Class 1 NIC is due only on relevant motoring expenditure above 55p per business mile (from 6 April 2026). Mileage payments for business miles count; whether the allowance itself counts depends on how your scheme works, so check with your payroll or tax adviser.
Under a company car on contract hire, the leasing company carries the residual value risk; if the employer buys outright, it carries that risk itself. Insurance, and any maintenance not covered by the lease, sit with the employer either way. Under a car allowance, vehicle ownership risks transfer to the employee. The employer retains the grey fleet duty of care under both models.
Start with your highest-mileage drivers and assemble the per-driver inputs for a representative sample: annual business mileage, vehicle grade, lease or allowance cost, fuel type, and compliance status. That is where the comparison stops being theoretical and becomes a number the finance committee can act on. For more on keeping those numbers under control once the decision is made, see how OviDrive approaches fleet cost control.
For savvy fleet managers looking for the latest trends and opportunities to improve their fleet's performance.


Copyright © OviDrive Group of Companies • Made with 💜 in Australia 🦘 • Operating in 36 countries and 3 continents 🌎
